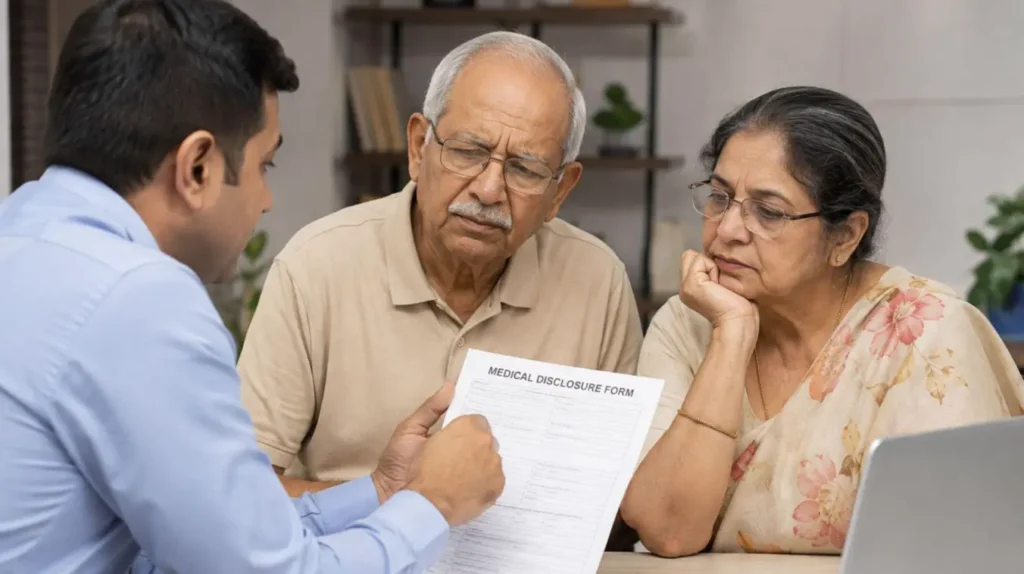

Medical disclosure plays a central role in senior citizen mediclaim because it helps the insurer understand the applicant’s health profile before issuing a policy. For older adults, past diagnoses, ongoing treatment, medicines and previous hospitalisation can all influence underwriting.
Sharing this information clearly supports a more accurate assessment of coverage terms. It also helps families understand what the policy may include, what conditions may apply and how the insurer could evaluate future claims under the agreed policy wording.
Importance of Medical Disclosure
A complete medical declaration gives the insurer relevant information about the applicant’s current and past health status. Families arranging a health card for senior citizens may focus on convenience, but the information submitted during policy application is equally important because it forms part of the underwriting record.
- Mention known medical conditions and ongoing treatment.
- Share prescribed medicines and significant medical history.
- Answer proposal form questions carefully and completely.
- Update the insurer if additional information is requested.
Pre-Existing Diseases
Pre-existing diseases can influence how an insurer evaluates a senior citizen’s application, especially where there is an ongoing condition, regular medication or a history of treatment. Even under health insurance for a family of 4, each insured member’s medical history may be assessed separately, which makes accurate disclosure particularly important for older family members.
- Disclose conditions already diagnosed or treated.
- Mention regular consultations or long-term medication.
- Provide available medical records when requested.
- Read policy terms related to existing conditions carefully.
Impact on Policy Approval
Medical disclosures help the underwriting team decide how the application should be assessed. The outcome may depend on the applicant’s health history, present condition, treatment pattern and the insurer’s underwriting framework. A disclosure does not automatically mean that coverage will be declined. Instead, it gives the insurer information to evaluate the application on its merits.
- Some applications may proceed on standard terms.
- Additional review may be required in certain cases.
- Further documents may be requested before a decision.
- Final approval remains subject to underwriting guidelines.
Effect on Premiums
Health information can also influence the premium offered for senior citizen mediclaim. An insurer may consider the overall medical profile while deciding the terms applicable to the policy. The impact can vary because underwriting takes several factors into account rather than relying on one health detail alone.
- The applicant’s medical history may form part of pricing.
- Ongoing treatment can require additional assessment.
- Policy features may affect the final premium offered.
- Premium decisions remain subject to the insurer’s underwriting approach.
Medical Tests and Underwriting
Medical tests may be requested when the insurer needs more information before completing underwriting. These tests can help clarify the applicant’s present health status and support a more informed assessment. They should be viewed as part of the evaluation process rather than as an indication of a negative outcome.
- Attend medical tests requested by the insurer.
- Share recent reports if they are specifically asked for.
- Provide accurate details about treatment and medication.
- Wait for the underwriting review before assuming policy terms.
Waiting Periods and Exclusions
Medical disclosures may influence the terms that apply to certain health conditions under the policy. Depending on underwriting and policy wording, an insurer may apply waiting periods, specific conditions or other coverage terms. These should be reviewed carefully so the policyholder knows how the cover works.
- Read the policy schedule and wording together.
- Check terms linked to declared medical conditions.
- Clarify waiting periods before completing the purchase.
- Ask for explanations where any policy condition is unclear.
Risks of Hiding Medical Details
Leaving out relevant medical information can create difficulties later because the insurer evaluates the policy based on the details provided at the proposal stage. If important facts are missing, claim assessment can become more complicated. Clear disclosure helps reduce uncertainty and keeps the policy record aligned with the applicant’s actual health history.
- Avoid guessing when answering medical questions.
- Do not leave known conditions out of the proposal form.
- Review the declaration before submitting the application.
- Keep copies of submitted forms and supporting documents.
Benefits of Honest Disclosure
Honest disclosure supports a smoother relationship between the policyholder and the insurer because both sides work from the same medical information. It also helps the senior citizen understand the coverage terms with greater confidence and reduces avoidable confusion during future policy servicing or claim review.
- The underwriting decision reflects the stated health profile.
- Policy terms are easier to understand from the beginning.
- Medical records remain consistent with the proposal details.
- Future communication becomes clearer when information is complete.
Conclusion
Senior citizen mediclaim works more effectively when medical information is shared clearly, accurately and at the right stage. Disclosing health conditions, medicines, treatment history and requested reports allows the insurer to assess the application within its underwriting framework. It also helps families understand how policy terms may apply before cover begins. Rather than viewing disclosure as a formality, applicants should treat it as an important part of buying suitable health insurance and maintaining a transparent insurance record over time with confidence.